

Every major shift in enterprise technology creates a multi-billion-dollar partner ecosystem. Not because tech vendors plan for it, but because new architecture creates new friction.
When technology was hard to source, we got Resellers.
When it was hard to configure, VARs created value.
As systems grew complex, Systems Integrators (SIs) built the bridges.
When enterprise IT got too painful to run internally, MSPs took the keys.
Cloud shifted the model to consumption and marketplaces. APIs created the integration partner. Automation gave birth to workflow orchestrators.
Now, the shift toward autonomous agents, MCP (Model Context Protocol), and AI orchestration is forming the next wave. But this wave carries a fundamentally different kind of friction.
From Connections to Delegation
APIs gave software a voice. Automation platforms gave software a schedule.
AI agents introduce something entirely different: agency. Software is no longer just passing data through a pipeline; it is interpreting context, picking tools, and executing actions on its own.
This is why MCP is becoming the most critical protocol in modern software. If APIs were the standard interface for app-to-app communication, MCP is becoming the interface layer for agents to discover and execute tools.
That triggers a brand-new set of ecosystem questions:
Who prepares an enterprise’s data and workflows so agents can safely consume them?
Who orchestrates multi-agent systems operating across disparate platforms?
Most importantly: Who is accountable when an agent gets it wrong?
The Delegation Paradox: Where Liability Lives
Every previous partner wave involved a human operator acting on behalf of the customer. A VAR configured the server. An SI wrote the custom code. An MSP clicked “deploy.”
Agents invert that sequence. An agent doesn’t wait for a human to confirm every step; it interprets context and acts.
This isn’t just a faster version of traditional integration. It is delegation. And delegation introduces liability.
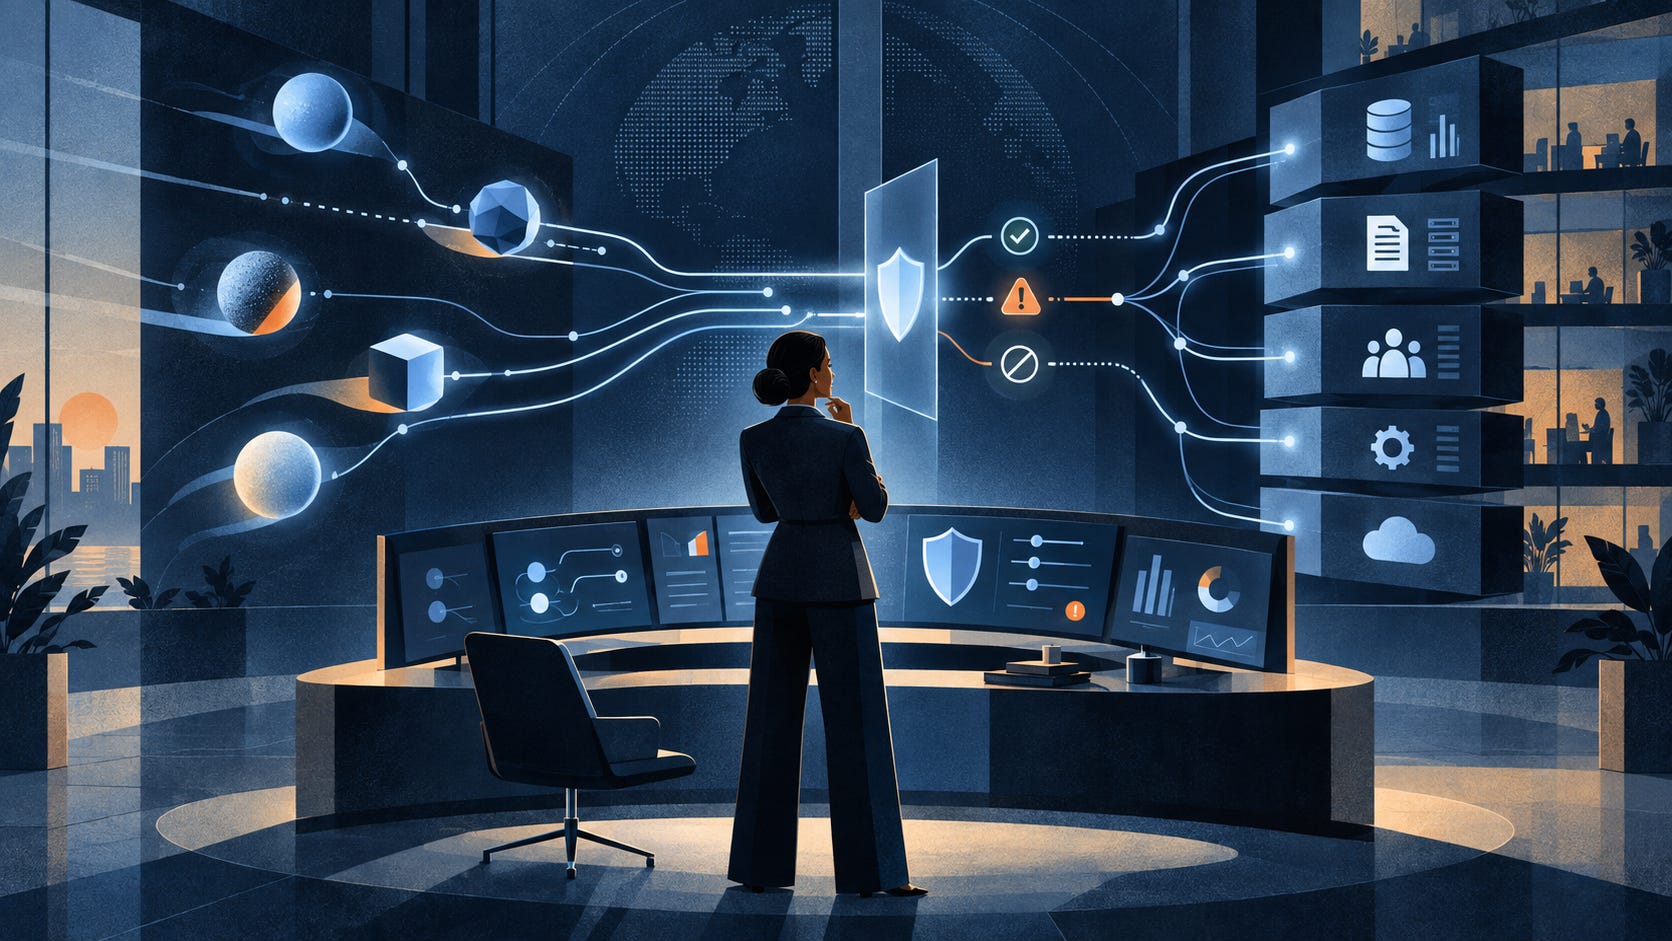
If an agent misinterprets an MCP tool context and executes an invalid transaction, issues a bad credit, or leaks sensitive data, the problem isn’t technical deployment; it’s governance, risk, and trust.
None of the legacy partner categories were built to hold that risk.
We don’t have a settled name for this new category yet (Agent Orchestrators, AI Governance MSPs, or Ecosystem Operators). But the pattern is undeniable, and the platform giants are already laying the tracks:
Anthropic opened MCP as an industry standard.
AWS launched its AI Agent Marketplace and wired its Partner Central into an MCP server.
Google Cloud added native MCP support across its agent suite.
OpenAI built its Apps SDK directly on top of MCP.
Microsoft integrated MCP into enterprise engines like Dynamics 365.
This isn’t a mature partner motion yet. It’s the early smoke before the fire, much like the first hyperscaler marketplace listings in 2016.
Will AI Eliminate Partners Entirely?
It’s worth confronting the elephant in the room: Will agents just do the partner’s job?
Yes, this wave carries higher disintermediation risk than any before it. Agents that can self-integrate and self-configure will wipe out low-value SI headcount and basic software resale margins.
But history shows us a clear rule: New capability creates new friction faster than it automates old work. The work doesn’t vanish; the friction just moves upstream.
Shift, Don’t Snap: The Hardware Lesson
It is also worth remembering that these transformations rarely happen overnight.
Whenever a breakthrough architecture arrives, the market tends to over-index on instant disintermediation. Consider the hardware industry. A decade ago, as workloads migrated to the cloud, conventional wisdom declared local hardware dead and traditional IT resellers on borrowed time.
Yet hardware didn’t vanish; it adapted.
As cloud bills ballooned, hybrid architectures stabilized, and specialized compute like AI clusters became table stakes, hardware didn’t just survive. It re-emerged at the center of the enterprise conversation. The partners who thrived weren’t the ones selling commodity boxes; they were the ones who shifted from selling hardware to orchestrating high-density compute, sovereign data centers, and specialized infrastructure.
The same transition dynamic will apply to agents.
Traditional SIs, MSPs, and VARs won’t be replaced by an agent deployment overnight. Instead, we’ll see a multi-year bridge where existing partners absorb agent capabilities into their current motions before entirely new, specialized category leaders fully emerge.
Transition takes time. But directionally, the vector is clear.
Follow the Value
To predict where the revenue goes, look at where the friction lives, and where new value is generated:
Hard to buy? Reseller (Margin / Markup)
Hard to deploy? VAR (Services Markup)
Hard to customize? Systems Integrator / SI (Project Fees / SOW)
Hard to run? MSP (Recurring Retainers)
Hard to connect? Integration & Automation Partner (Usage / Licensing Fees)
Hard to trust, govern & coordinate agents? The Next Partner (Outcome-Based / Value Share)
Nobody has solved the business model for this next layer yet. Will they charge subscriptions like SaaS? Project fees like SIs? Or take a share of the actual business value an agent creates?
Whoever answers the monetization question first won’t just build a huge business, they will define the category.
Technologies change. Interfaces change. Labels change.
But the core rule remains: Partners don’t just follow friction, they follow where value is being created.
The Takeaway: Don’t ask what work AI will take away from your partners. Ask where your customers will experience the newest, highest-stakes friction when agents run wild, because that’s exactly where the next generation of value creation (and partner revenue) is hiding.
Really thoughtful piece, Rob. And then who/what manages
"Hard to trust, govern & coordinate agents? The Next Partner (Outcome-Based / Value Share)" especially to your point coordinating but then also knowing which one to deploy within which context.